

Table of Contents
ToggleBorrowing during the festive season is not a bad thing. It is a tool. The tool, however, must be used with discretion. This guide will help determine when a personal loan for Diwali is a good idea, how to borrow smartly, and what to look out for before hitting the apply button.
Why Diwali costs come so fast
This is where many find themselves in a spot. Not wanting to say no to their family while not wanting to raid their emergency savings. A Diwali expenses loan is a good way to spread out a large festive expense over a few months instead of paying a large chunk all at once.
What is a Diwali shopping loan?
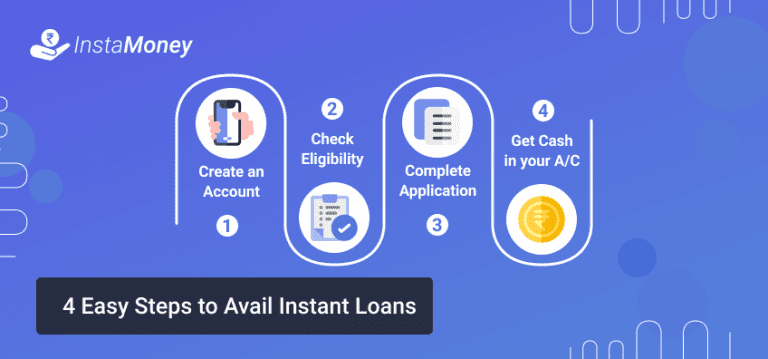
InstaMoney connects you to trusted NBFC lending partners, who are the actual lenders. So when you take an instant loan for festive shopping on the app, the money is transferred by an NBFC partner, while InstaMoney ensures that the whole process is seamless and digital.
When to borrow for Diwali
- You have a steady income to repay the EMI
- You need a good thing now and want to repay it over a period of time
- You don’t want to use your fixed deposit or emergency fund.
- You are buying it for show, and you are already stretched thin.
- You haven’t thought through how you will repay the EMIs.
- You are borrowing for the sake of borrowing as credit is available.
A personal loan for Diwali should be a good thing, where you borrow to enjoy the festival, but shouldn’t leave you with debt to worry about as the new year begins.
How to use a Diwali loan responsibly
Set a festive budget
Before looking at any loans, it is essential to set a festive budget. List out what one intends to purchase and the approximate cost. Having a number in mind will stop you from borrowing more than you intend to.
Borrow only what you need
It can be tempting to borrow a larger amount, so avoid the temptation. A smaller Diwali expenses loan will have smaller EMIs that are easy to repay.
Check your EMI
Use an EMI calculator to estimate what your monthly payment to the lender will be. Keep all your EMIs together as a small portion of your monthly income so they don’t become a burden. If the EMI is too large, reduce the amount of the loan or extend the tenure.
Read the Key Fact Statement
Under the RBI’s digital lending guidelines, one must be given a Key Fact Statement before signing the loan contract. The KFS contains the Annual Percentage Rate (APR), which is an all-inclusive rate that shows the true cost of the loan, including interest rates, processing fees, and other charges. Read the KFS thoroughly. A legitimate lender will not charge any fees that are not explicitly mentioned in the KFS.
Know the fees and interest
Personal loans typically come with interest and a processing fee. Interest rates are based on one’s profile and credit history. Read the processing fees and interest rates carefully on the app before applying because they may change. Honest lending should have clear, upfront terms with no hidden costs.
Plan your repayment
Set a calendar reminder for the EMI due date and pay on time every month. Timely repayments will protect your credit score and ensure lower interest rates on future loans.
What to check before you apply
Eligibility
Most lenders will require that an applicant is an Indian citizen, between the age of 21-55, employed (salaried/self-employed), with a valid PAN, Aadhaar and bank account.
Total cost
This includes the interest rates and any applicable fees. APR takes this into account.
Tenure
Keep in mind that a shorter tenure has larger EMIs, but will save you money on the overall interest paid.
Cooling-off period
Under the RBI’s digital lending guidelines, one has a short period of time to cancel the loan contract. This means one can exit the loan agreement by repaying only the principal and the applicable APR without any additional penalties
Grievance process
A legitimate platform will have a clear process on how to file a complaint, which should be clearly stated on its website/app.
A calmer, smarter Diwali
The aim is to enjoy the festival without financial stress. A Diwali shopping loan can help achieve this goal, as long as one borrows wisely with a repayment plan. Using a personal loan for Diwali is a bridge, not a crutch. In case the numbers work for your monthly budget, an instant loan for festive shopping can help you enjoy the present while repaying it in easy instalments.
With InstaMoney, checking eligibility for an online personal loan takes a few minutes with the whole process being digital. For a personal loan for Diwali, InstaMoney connects you to trustworthy NBFC lending partners, which can offer you an instant loan against a few documents. This Diwali, let your spending be joyful and your borrowing be wise.