An unexpected expense can put even a carefully planned retirement budget to the test. Whether it is a medical bill, a home repair, or a family commitment, arranging funds without disturbing regular expenses requires thoughtful planning. Loans for pensioners may be one option to explore, but the important questions often arise before an application begins.
How much can you comfortably repay from your pension? What eligibility conditions might affect your application? And how do you compare borrowing options without overlooking the costs? Knowing these factors can help you make a more informed decision about your financial needs.

What Should Pensioners Check Before Choosing a Personal Loan?

Before comparing loans for pensioners, it helps to work with your actual monthly numbers rather than the maximum amount a lender may offer.

Start with three figures:
Work Out What to Include
Monthly Pension
Available
Regular pension credited to your account
Essential Monthly
Commitments
Healthcare, groceries, utilities, insurance, rent, and existing EMIs
Comfortable EMI Amount The amount you can repay while retaining money for regular and unexpected expenses
For example, receiving a pension of ₹50,000 does not mean the entire amount is available for repayment. If ₹34,000 already goes towards regular commitments, look at the remaining amount before choosing an EMI.
This also helps when selecting the tenure. A shorter tenure can increase the monthly repayment, while a longer tenure spreads payments across more months. Compare both the EMI and total repayment before deciding.

Checking your personal loan eligibility beforehand can also help you understand the factors likely to shape the amount and tenure available to you.

Does Your Pension Type Affect Your Loan Application?

Not all pensioners receive their pension income in the same way. Some might receive a central or state government pension, a defence pension, a family pension, or a pension from a private employer. The type of pension you receive can impact the required documents a lender requests and how your income is assessed.
Before you apply for an instant personal loan for pensioners, check these three things.
RBI also advises borrowers to check if a digital lending app is associated with a regulated bank or NBFC through the lender’s official website before applying.

Why Do Lenders Ask for PAN for a Personal Loan?

1. Identify Your Pension Category

Government Pension
Keep your Pension Payment Order (PPO), pension slips, and bank statements ready where required.

Defence Pension
Check which pension records, such as your PPO or other accepted pension documents, the lender requires.

Family Pension
If you receive a pension after the death of a spouse or another eligible family member, confirm whether the lender accepts it as income and whether additional documents are necessary.

Private or Corporate Pension
Ask whether the lender accepts your retirement scheme as a source of eligible income and which records establish the amount you receive.

Do not assume that every lender accepts all pension categories under the same conditions.

2. Match Your Pension Records With Bank Credits

Compare the amount shown in your pension documents with the credits in your bank account. If you notice deductions, arrears, or changes in the credited amount, clarify them before submitting your application. Keep recent bank statements and any supporting pension certificates available if requested.

3. Calculate the Income Available for Repayment

Your total pension income is not necessarily the amount available for an EMI. Account for deductions, healthcare costs, household expenses, and existing loan repayments before deciding how much you can borrow. If you receive additional retirement income, ask whether the lender considers it when assessing your application.

Finally, check the lender’s age limits, income requirements and other conditions for pension loan eligibility. Reviewing the personal loan eligibility criteria can help you prepare before applying.

Remember that submitting the required documents does not guarantee approval. The lender makes its decision after assessing your income, repayment capacity, and application against its eligibility criteria.

What Should Pensioners Compare Before Applying?

Once you have an EMI range in mind, compare the complete loan rather than focusing on one number.
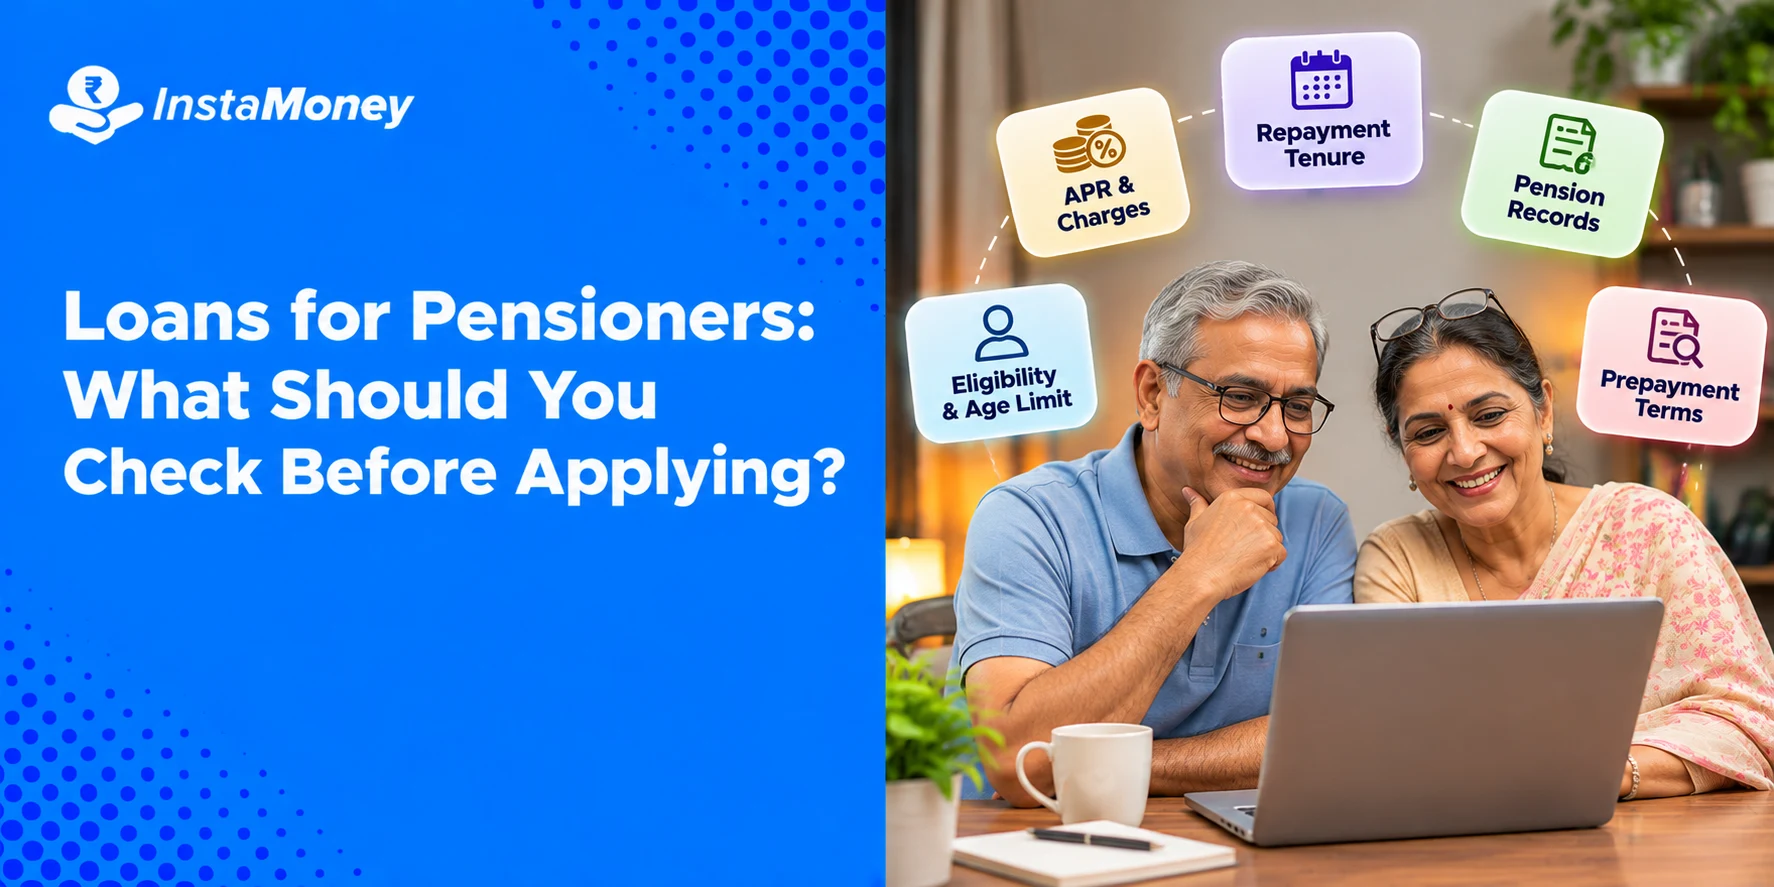
For loans for pensioners, review:

APR and Charges
Look at the Annual Percentage Rate (APR), processing fee, and other disclosed costs together.

Repayment Tenure
Check how the available tenure changes the EMI and overall repayment.

Age at Final Repayment
Confirm the lender’s age requirement for completing the loan.

Prepayment Conditions
Understand how an earlier repayment would be handled.

Key Facts Statement
Use the KFS to compare important costs and repayment terms on the same basis.

Documents Required
Keep PAN, Aadhaar, pension records, and relevant bank statements ready where required.

It can also be useful to check eligibility before starting several applications. This gives you a clearer idea of the criteria you meet without treating the highest available amount as the amount you should necessarily borrow.

If you are considering an instant personal loan, the digital process can make application and document submission more convenient. The borrowing decision itself should still come down to the amount, tenure, EMI, and total repayment that work with your pension income.

Plan the Repayment Around Your Pension

Loans for pensioners can support medical expenses, home requirements, family needs, or other planned costs when additional funds are required. Before choosing one, work out the EMI your pension can comfortably support, then compare tenure, APR, charges, and age-related criteria across available options.

If you would like to explore personal loan options, InstaMoney can connect you with RBI-regulated lending partners. Review the lending partner’s eligibility and loan terms before proceeding.